Tuesday, March 30, 2021

Good writers on SeekingAlpha.

Good writers are hard to come across. The ones with too many followers are trash and just following FADs. There are many that pump out articles because they make money per article (think of Chinese sweat shop.) Many don't even invest in the stocks they recommend! 


Two that I follow, after many hours of deep research:

Jolyon Loo

Carleton Hanson

These two give quality reports on companies they are long. They are fully invested in their companies. They have a near perfect track record, their reasoning and value investing principles is absolute. 


Comment who you know, we can add it to the list.

Monday, March 29, 2021

How to get free stock research from earnings calls.

Example:

$MEDS on NASDAQ


1. https://seekingalpha.com/article/4381486-trxade-group-inc-meds-ceo-suren-ajjarapu-on-q3-2020-results-earnings-call-transcript

2. Taglich Brothers- https://taglichbrothers.com/companyreports/trxadegroup/trxadegroup-11022020.pdf

Dawson James Securities- they took it off their website, but they have a bunch of free ones. https://dawsonjames.com/reports-landing/

Dougherty & Company- nothing there. but it's supposed to be free. 

Lake Street Capital Markets- don't give free research. 


Steps:

1. Locate quarterly earnings calls transcripts on Seeking Alpha free 

2. Identify call participants analysts. Their firms give free reports. 


I was stumbling by when I found this by accident. 

Sunday, March 28, 2021

$ODT Odonate Therapeutics. Keep your eye on it.

Net cash: $114 MM

Market cap: $119 MM                Almost a net-net. 

ODT is a really weird stock. But it can be a net-net. Watch out! I am watching out! It's a biotech stock that stopped it's pipeline drug because FDA won't approve it, so the stock tanked! Literally (-80%). 

1. Why it's weird: A lot of insiders bought at the $15-17 range. *


Source 1:

I did the math for you, excluding BOX CAPITAL LLC, insiders (2) bought $50 million dollars worth of stock (Boxer bought $35 million). Mean price $16/share. 

Then all of a sudden the stonk tanks to $3. From $20. 


Why would insiders buy to lose money, I don't know. It is definitely not going back to $20. 

Apparently, "Odonate is discontinuing the development of tesetaxel and will wind down the operations of the Company." According the SEC filing 8k on March 25th 2021. ** "Odonate estimates that the Restructuring will be substantially complete by June 30, 2021 and that costs incurred in connection with the Restructuring will be approximately $14 million." Key word. $14 million restructuring cost. 

Apparently this is their only drug in their pipeline and people think it's going to go bankrupt. But little do they know their cash position.


2. Little do they know they have $150 million in cash...

Cash position: $157.3 MM + $2.6 MM Prepaid expenses = $160 MM cash position

Total liabilities they are obligated to pay: $31.74 million


Source 2: TIKR, you need an account, make a free account at the bottom, I gave you my referral code. I gain nothing. 

but don't forget restructuring cost is $14 MM. 

160-31.74-14 = $114 MM net cash position (after all liabilities.) 

But market cap is only $119.3 MM!!!!!

Ok it's not a net-net. It's almost a net-net. Watch out. 

**** I'm excluding the $7 MM in PP&E and $1.71 in other long term assets (I don't know what that is.) I don't know if it's worth fair value.

Their average cash burn rate is $30 million/ quarter, but since majority is of research and development, they are stopping that. So cash burn rate will be minimal? I only expect the $14 MM to be a cost. 

Negative EBITDA of -$30 MM a quarter, implying cash burn rate (depreciation is negligible, I look at the cash flow statement.)


https://stockanalysis.com/stocks/odt/financials/balance-sheet/?period=quarterly

They just did an equity raise in Q3 2020 for $88 million.


3. Interesting call options chain: many more open call options than put options. 

Many call options. Show yahoo options chain. People expect stonk price to go up? 


Source 2: Yahoo finance options chain.

That's why it's so weird, insiders lost so much money, and now it's almost a net-net because people think it's going to go bankrupt. 

What to make of this? If market cap drops drastically below $114 million, this will be a good feast. I need a large margin of safety to make this work, because these guys might take a chunk of cash for themselves. 

Sources:

Source 1: https://finviz.com/quote.ashx?t=ODT,ITOS 

**https://sec.report/Document/0001564590-21-015499/

***TIKR account: https://app.tikr.com/register?ref=9bsel3

Friday, March 12, 2021

Short squeeze + insider buying + 52 week low = $$$$

 Buy into the short squeeze. 

THIS IS NOT A NEW IDEA. HEDGE FUNDS HAVE BEEN DOING IT FOR DECADES. Look at Tilray, OSTK, GSX, GME, Blue apron holding. All short squeezes. Many more that I haven't heard of.

What's the idea? Market thinks it's so bad that's why everyone is shorting it. But insiders are buying? Because they know better and the stonk is undervalued. It's at a 52 week low and short interest is still so high. Shorts are going to have to buy back in, elevating stock price, at least temporarily. We play this by buying long dated call options just in case. Look for unusual options volume (call volume), it will be interesting to see if other people think the same (short squeeze.)


Remember key components:

-High short interest

-Insider buying (not one guy, but multiple people to solidify bullish position.)

-52 week low. It can't go lower, can it? Shorts have to buy back in, crowding exits. 


For those of you less inclined: https://finviz.com/screener.ashx?v=111&f=sh_insidertrans_pos,sh_short_o20,ta_highlow52w_b40h&ft=4


I will show some examples to concretize this idea so you really understand it/ believe it. Also for myself too. Follow my trades (if I make any.)

Remember, these are only quantitative facts, we need qualitative catalysts for this to really work. Like Ryan Cohen owning 10% or Michael Burry taking a position. We got to look for Form SC 13 G or D filings. 


This is extremely unrefined, many more metrics to look for like liquidity (low volume, wide bid-ask spreads), high insider ownership. Many more, I just can't remember. I will update it the more I do it. 


THIS IS NOT INVESTMENT ADVICE. 

Buy depressed IPOs after a year (or two.)

There is a study that shows most IPOs draw down before going up. Let's find those depressed IPOs that have significant insider buying and significantly lower than their 52 week highs. So we can invest in them.


For those of you less inclined: https://finviz.com/screener.ashx?v=111&f=ipodate_prev2yrs,sh_insidertrans_pos,ta_highlow52w_b40h&ft=4


This has brought me to three options:

GSKY

and PROG. 

And MPLN (SPAC beware). I like all three. 


They all have significant insider buying enough that it matters. I filtered it out. It's best. Usually means stonks go up. **Usually**, not always. Almost always. 


Don't know what these are? Read articles on SeekingAlpha for free. MPLN doesn't have any free articles. Read this instead: https://yetanothervalueblog.com/2020/12/multiplan-part-1-short-squeeze-potential-mpln.html. 


I am probably going to buy call options on those. MAYBE. This is not investment advice. I want to. 


Usually IPOs depress after their lock-up period expires because insiders (and private investors who owned the company before going public) start selling. Look for this https://www.marketbeat.com/ipos/lockup-expirations/. List of lock up expirations. 


If I forget anything, I will update it here. Put it in the comments. 

Thursday, March 11, 2021

Investing in spinoffs-- profitable.

Example: https://www.youtube.com/watch?v=73zjEN98FFc  my youtube channel

There is a lot more information than the little given here. I need to gather my thoughts. I have very specific information.

Look at Form 10-12B https://sec.report/Form/10-12B#more

Shows you all the recent spinoffs. Spinoffs outperform the market in general. Look for insider buying after the spinoff and high management ownership and same management running the business. That means they are comfortable owning the business. Usually in a spinoff there is indiscriminate selling by institutions because it doesn't meet their mandate to hold the stock (too little market cap, different industry, higher volatility, etc.. others.) So there is significant selling pressure in the beginning of the spinoff and not enough liquidity to capture it fast enough**. Therefore stock price is depressed temporarily. Capture it. It doesn't stay long.

What you want to look for is smaller cap companies and companies with lower trading volume and because small volume spikes itself will boost stock price. Illiquidity has its perks. Often times microcaps have a boost in stock price after the initial sell-off because illiquidity is more pronounced and when selling the bid-ask spread is horrible.

Some names that I used to own:

CNXC
VNT
AOUT

Best one is CNXC in my opinion. I am not holding any of these currently. I am 100% cash. This is not investment advice. 


See stockspinoffinvesting.com for more information. Free. 

Follow SC 13D filings to make money.

Find Form 13D: https://sec.report/Form/SC+13D


Many people know insider trading and follow that. Form 13D is something new, something peculiar and something that surely works. It makes sense. 

Whenever an activist investor acquires more than 5% of a company, he must report a Form SC 13D filing within 10 days. He must state his intent for his purchase of 5% of the company and if he's going to buy more. Key part. 

If a large investor is building a position we can front run him. Ta da! That's it. Buy stock or options whichever is applicable. I've seen this before that's why I'm saying. Not just theoretical. 


Main requirements/additives:

-High call options volume (look for specifically ITM and OTM if it's illiquid.)

-If liquidity is low (volume is low, bid-ask spreads are wide, usually there will be a spike in share price as the investor tries to acquire more shares.) 


Reasoning:

Usually the hedge fund/ investor will buy lots of call options to hedge against price movement so he can buy lots at the current stock price and/or stock option strike price. Look for ITM options with close expiry or in general high open interest in OTM call options if their is liquidity risk. If the bid-ask spreads are wide and any jump in volume can jerk the stonk price higher.

Happy Hunting! We need to create a screener for this. Will be amazing. 

Wednesday, March 10, 2021

Does P/B even matter?

Not to me, it doesn't!

P/B is liquidation value compared to market cap. 

If P/B > 1, you lose money. If P/B < 1, you gain money, considering you can sell assets at fair market value, which you can't. 

I buy a company for its future cash flows, not it's liquidation value. I am not going to liquidate the company, unless I do. Unless corporate raiding.

That's why tech stocks have high P/B, not much infrastructure/machinery, just high future cash flows. Much better than manufacturing companies. Better margins. 

Find SPACS under $10 on finviz. Stonk screener.

https://corpgov.law.harvard.edu/2020/11/19/a-sober-look-at-spacs/

Read this article as a precursor. Shows you how much of a scam it is. 

https://finviz.com/screener.ashx?v=111&f=ind_shellcompanies&ft=4

If a SPAC doesn't acquire a company within two years, they return your $10 plus interest.

So what you got to look for is companies that are about to expire their two years and are trading under $10. Then you get free money when it expires.

What if the SPAC acquires a company and the share price tanks? Welp, good luck. 

Do it yourself if you're a big boy:


A company that never pays a dividend is a ponzi scheme.

It doesn't need to pay a dividend now. It doesn't need to pay a dividend tomorrow, but if it never pays a dividend until the day it dies, it is a Ponzi scheme. Let's use an example to solidify (real life example.)


Definition of a Ponzi scheme: Investor A makes money off investor B. Investor B makes money off investor C. Investor C is a bagholder. See image 1. 


Real life example: https://www.youtube.com/watch?v=EjOamcE0ahE&t=551s Ticker: MSN Emerson radio

You don't need to watch the video. I will explain everything right here. 


How do you make money from stocks? Either through capital appreciation or dividends. Let's ignore capital appreciation because it's just another investor paying you more for it (Ponzi scheme.) That means the only way to derive value from a company is through its dividends. Dividends is what you get from the company. The company gives you cash from its balance sheet. What happens if a company has a $1 billon in cash but never gives it away as dividends and never intends to? The value of the cash might as well be zero (even if it gets acquired, the parent company won't give you a dividend either. Got 'em!). How does this happen you may ask? Easy. Insiders own 60% and never issue a dividend, rather milk the company through salary (see listed video.) 


What about stock buyback? Isn't that the company giving back to its shareholders--- yes as long you are one of the guys selling your shares to the company. Otherwise no. If you keep holding your shares, it's  a waste. It's a Ponzi scheme. The only way you can make money is if you sell it another fool at a higher price. 


You may not understand this concept thoroughly because I did not explain it right. But you better know it, it is essential. Many people don't know and they fight with me on reddit. 


That means the money they got from their IPO is essentially free money they never have to repay (good deal! Where do I get that?)


That's why when I see a cyclical company that never pays a dividend, I cringe. Ponzi scheme *100.


Appendices:

Image 1. Sorry bud. You're the bagholder. 


Saturday, February 20, 2021

Saturday, February 13, 2021

People to follow

Hussmann funds -- macroeconomic picture. amazing stuff. proper articles. he manages his own fund. 

Bonsai Partners--- concentrated portfolio. Amazing returns. One guy. read his investment letters. 1/quarter.

Alta Fox Capital--- microcaps. Amazing research. Free. Go check it out yourself.

Tuesday, January 19, 2021

Investing in growth stocks. Identifying good companies at good valuations.

I look for this when I buy growth stocks. 
I haven't invested in any growth stocks...yet! Waiting for the crash, then will pick up Square (SQ) cheap. Or anything. 

I look at these three specific criteria on finviz: 
  1. Gross margin over 30%. 
  2. Past 5 years sales growth over 15%. (CAGR > 15%.)
  3. P/S = 4 or lower. I will tell you why, there is a very specific reasoning. 
There are many more metrics. Less debt, high insider ownership, but I don't want to exclude good companies. 

Reasoning:

1) A good high margin business means over time as scale is reached, more profits will fall down to bottom line (profit.) Operating margin will gradually improve, I am not worried. Look at Mastercard. 

2) This defines growth stock. I want it to grow insane. I expect it to grow exponentially going forward. 

3) P/S = 4 cannot be more than 4. This is valuation. I cannot overpay for a stock. Obviously I want to pay cheaper but I find that good growth stocks never reach p/s below 3-4. I have studies. If you can catch some at the level, it's crazy. Obviously for the very growth stocks we can pay up. We have to pay up. But otherwise p/s = 4 is good. 

If it's in its early stages of development low debt will make sure it doesn't eat itself up. For young growth stocks it is essential that there is high insider ownership to make sure the company goes right in the long term and not guided by short term incentives that can hurt itself. Not necessary, but always something to see. If the CEO has $10,000,000 worth of stock, he will wake up at 2 am to take care of his baby.

Earnings is not necessary (net income.) I expect them to improve their margins quickly so that EBITDA is positive. Often what you see is that the really good companies have positive ebitda immediately, so that they don't burn cash. They do burn cash to grow aggressively. If you look at Amazon, Facebook, all had positive ebitda almost immediately. This is the sign of a sustainable company. Not necessary, but comforting. It lives off its own cash, it doesn't need cash injections (equity+debt). 

Study:

CRM- lowest p/s it ever went- 3.09    2009 crash
FRPT- p/s = 2.04                                 2016 shortly after IPO (lock-up)
MA- p/s = 3.52                                    2008 crash
MSCI- p/s = 3.44                                2008 shortly after IPO and crash
SQ- p/s = 2.19                                    At IPO, never got cheaper

Many stocks out there that never dipped below p/s = 4. We have been in a crazy overvalued bull market. Things are always priced in years ahead because of low interest rates, pension funds and endowments and other "safe" investors come into stock market for yield because there's nothing in bonds. 

BBGI is a scam. You must read the 10-k.

tl;dr scammy related third party transactions. 

I made a YouTube video about this. You don't need to watch it because everything is covered in the article. 

Welcome back stonkers.

We all love investing. Some love investing in hyped spacs. Some love investing in overvalued tech stocks with p/s = 60. Whatever it is, we all "invest" in hopes of making money. 

BBGI is a scam. Beasley broadcast group, a radio station company. And you won't know if you never read the 10-k. The financials look good, that's what brought me into the stock. I found it on finviz.com. 

This article will illustrate why you must read the 10-k (annual report.)

Some key things to note. I will tell you the important things. Everything is provided proof in the footnotes. 

  • Essentially this is a company that makes money by advertising on their radio stations. Figure 1. Page 4. 
  • It is run by a family. Insider owns 60% of the voting control. He controls the company. ***key metric. Figure 2. Page 17.
  • Main part: BBGI invested $1.3 million into Digital PowerRadio LLC, a company owned by Mark Fowler, a director of BBGI. The company dissolved itself, the patents are useless. December 2019 BBGI wrote it off as a loss. This is screaming conflict of interest. Figure 4. Page 54. 
  • Main part: BBGI sells towers and radio stations to the Beasley private LLC. Then leases it back for ludicrous valuations: figure 5. Page 18. See "related third party lease." 
    • They sold radio station in Charlotte, NC to private LLC for $400,000. Leased it back for $100,000/yr. Lease expires in 2025! They make their money back! Figure 6. Page 54. 
    • They claim that the terms are as favorable as getting it from a third party. Bullshit!!!! Figure 7. Page 29. 
    • They rent their principal executive office from private LLC for $200,000/yr. Figure 8. Page 53. 
    • They lease a tower for 19 radio stations for $400,000/yr. Figure 9. Page 54. 
    • They lease property for radio stations from private LLC for $200,00 yr. Lease expires 2024. Juicy cash flow. Figure 10. Page 54. 
    • They lease towers for one radio station in Tampa, FL, from private LLC for $31,000 yr. Lease expires 2025. Figure 11. Page 54. 
    • They lease towers for two radio stations from private LLC until 2038! Rental expense in 2018 is $100,000/yr. Rental expense in 2019 is $200,000/yr. They increased it by $100,000 wtf. Figure 12. Page 53.
    • Their third party lease with an unknown party is so much cheaper. only $13,000 for 2018 and $11,000 for 2019. Figure 13. Page 54. 
    • BBGI leases several towers for one radio station in Boca Ration, FL. Rental expense $100,000/yr. They sold it to private LLC in 2006. Milking the cow. Figure 14. Page 54.
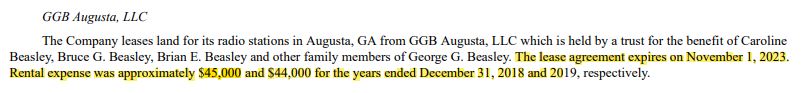
    • BBGI leases land from private LLC for $45,000/year. Lease expires 2023. Figure 15. Page 54.
    • BBGI leases property in Lase Vegas from private LLC for $200,000/yr until 2023. Figure 16. Page 54.
In summary:

BBGI sells land, tower, radio stations to its private LLC and rents it back at ludicrous rates, all the while locking in long expirations. They get their money back. Look at the examples above. There is one incident where BBGI dumped $1.3 million into a related company owned by the director of BBGI and immediately wrote it off as a loss. Something is very wrong. Hidden behind closed doors.

This is a microcap: market cap is $58M as time of writing (Jan 19 2021). Often this microcaps have no coverage by analysts. That is why it is essential you must do your research. This information cannot be found online-- I searched! Some people posted about it on SeekingAlpha-- check it out it's a free website where writers post their thoughts/articles about companies. Applies to all companies. 

Insider are milking this company. That's why you must the 10k.

Peace out stonkers. - stonk slayd

footnotes:

Figure 1. 


Figure 2. 


Figure 4.


Figure 5.


Figure 6.


Figure 7.


Figure 8. 


Figure 9. 


Figure 10. 


Figure 11. 


Figure 12. 


Figure 13. 


Figure 14. 


Figure 15. 


Figure 16. 


Friday, January 1, 2021

What to buy in a market crash? - short read 4 mins.

 ***I have a request for you at the bottom.***

When a market crashes, stonks go down. Image 0.

Image 1. For those you less inclined, I put a visual for you to understand better. Image from finviz. Two metrics: stock price less than 70% 52-week high. And insider buying. Also, as an extra I look for dividend paying stocks (showed in image 1) so that I get dividends while I wait for stocks to go up.

Where do you get insider buying data for NYSE and NASDAQ? openinsider.com and finviz.com.

They come from form 4, and these websites compile it for you.

Let me show you some examples. 

What does this get you? This gets you stock that the market thinks is bad, but the insiders know better and are buying their stock hand over fist. Insiders are corporate insiders (CEO, COO, CFO, CIO, CMO, VP operations, VP internal external, and directors.) Deeply undervalued stocks. Just this March Corona-beer (see image 2) crash so many insiders bought at depressed stock levels and now they are up 200%, 300%, 400%, and beyond 1000%. Insiders are not stupid, they don't buy stock to lose money. They buy stock to make money. They only buy if its profitable. Remember, on top of their stock compensation, on top of their stock options, they go out and buy open market buys of stocks, that means they are really convicted, sure of themselves.

During a market crash, there is a lot of uncertainty. Usually the bubble pops, perhaps an economic downturn, and many companies may go bankrupt if daddy J. Powell doesn't step in and turn on the money printer (unfortunately.) Refer to image 3. 

What to look for in insider buying:

This is very important. Don't just buy every stock that insiders buy. You must look for multiple insiders buying stock. Not just one insider buying the stock. You want them to buy a sizeable portion, not just a small bit. They need to buy with conviction. Like this: 


$DCP nyse stonk up 750%.

$COWN nasdaq stonk up 350%. 


Multiple insiders buying and sizeable amounts (lots of insider buying.) No baby buying. 

Obviously I do own my financial analysis with these guys before buying stock.

*also it is not a bad idea to look for companies that have low debt (low D/E ratio) because in a market downturn it is hard to get refinancing and it is very expensive. Better to have cash. 


Let's change the name to stonk market. Sign this petition. http://chng.it/jhqynPGhJ2. Every vote counts. You matter!

Appendices Images.


Image 0.


Image 2.


Image 3. 

Sunday, December 27, 2020

Prayer for JPOW


 Genesis 4:20 Jerome Powell

Our father J. Pow, who art in heaven, hallowed be thy name,

Thy printer on, thy tendies done, just in time for market open,

Give us this day our daily pump, and forgive the gay bears for their puts - 

as soon they shall buy calls,

And lead us not into poverty, but deliver us away from the holding of bags

 into the land of glorious tendies,

J. Pow spoke "brrrrrrr" and it came to be.

a-men.

J. Pow saw all that he had made, and it was very good.